- CRE Daily
- Posts
- Industrial Market Steadies as Supply and Demand Find Firmer Footing
Industrial Market Steadies as Supply and Demand Find Firmer Footing
Rents are still climbing, supply is moderating, and e-commerce is doing some heavy lifting.
Nina Dale
October 05, 2026
In partnership with

Good morning. E-commerce is giving industrial real estate another tailwind, reaching a record share of core retail sales. That growth is helping support logistics demand as the broader market works through its supply boom.
🎙️ No Cap Encore: While the guys take a short break, we're revisiting No Cap's most-watched episode to date: Bob Knakal on NYC real estate, dealmaking, and four decades in the business.
CRE Trivia 🧠
Which first Treasury Secretary championed the 1791 charter of the First Bank of the United States?
IN PARTNERSHIP WITH REAL PROPERTY CAPTIVE
The fastest way to add $6 million to your portfolio
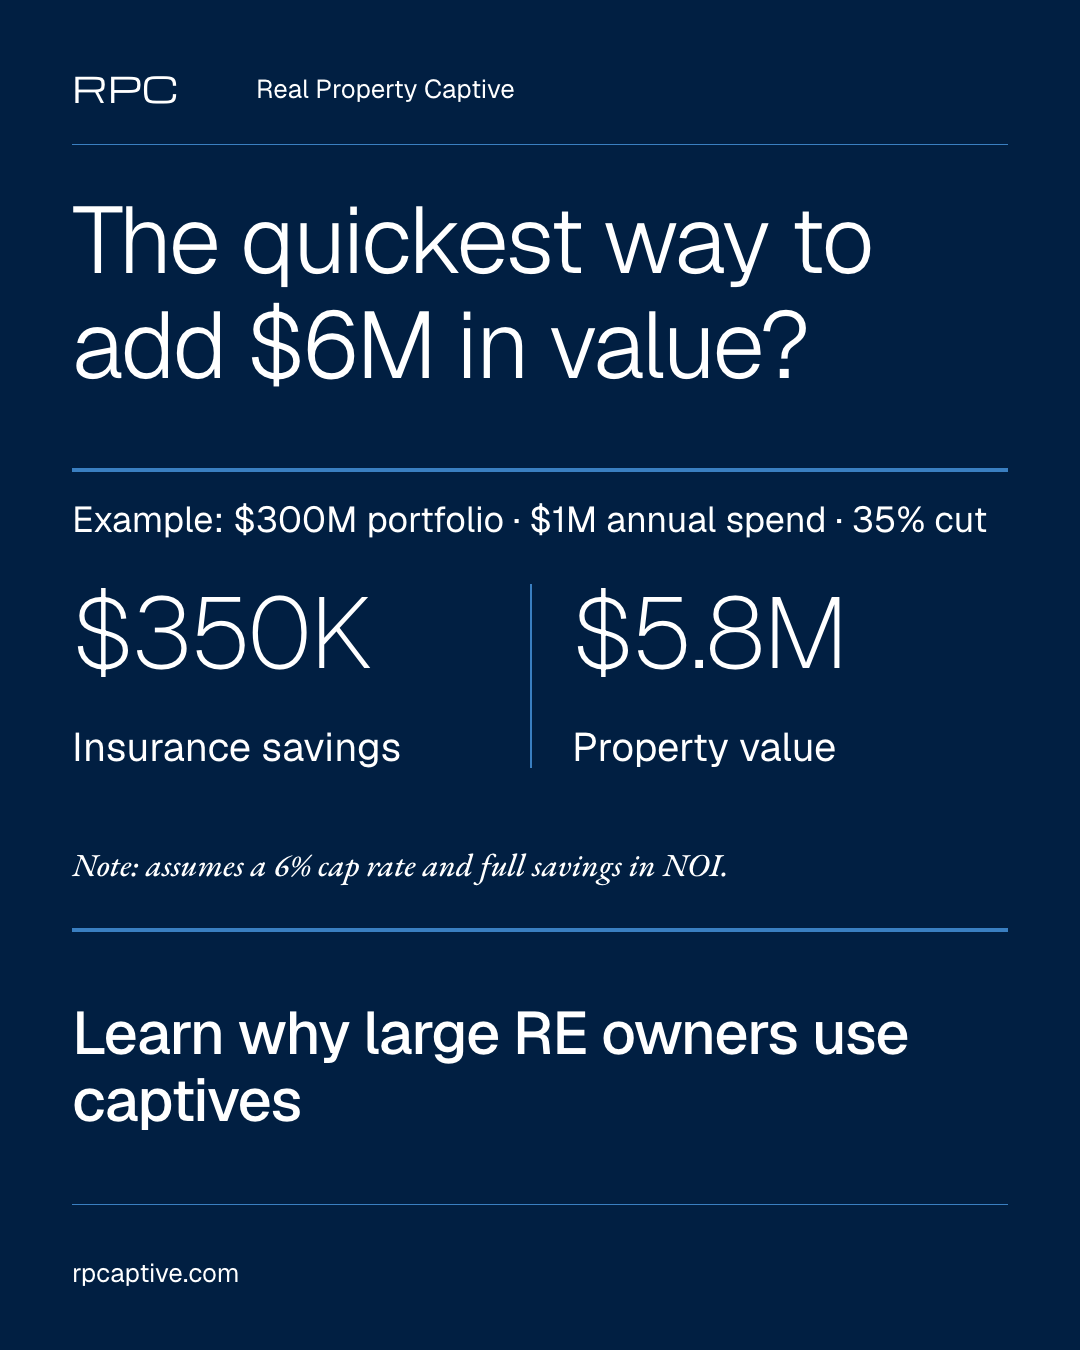
Improve your NOI by buying insurance the same way institutions do. Captives.
Cut a $1M premium by 35%, and you add $350K to NOI. At a 6% cap rate, that is $5.8 million of value. No new leases, no capex, same high interest rates.
For decades, institutions and roughly 90% of the Fortune 500 have bought insurance through captives: they own the primary insurer, buy reinsurance in bulk, and keep the premium they don't use. Middle-market owners were shut out.
Real Property Captive is an A-rated, owners-only group captive that brings that program to middle-market CRE, with rates up to 35% below what you pay today.
See what your portfolio would save at rpcaptive.com. Open to $100MM to $3BN portfolios with demonstrated low loss histories.
*This is a paid advertisement. Please see the full disclosure at the bottom of the newsletter.
Market Snapshot
|
| ||||
|
|
Finding Balance
Industrial Market Steadies as Supply and Demand Find Firmer Footing
The industrial market is settling after its historic building boom, with resilient demand, disciplined development, and e-commerce helping absorb new supply.
By the numbers: National industrial rents averaged $9.31/SF in August, up 5.4% YoY, while vacancy held at 9.3%. Atlanta led major markets for rent growth at 7.9%, followed by New Jersey and Miami at 7.6% and Dallas at 7.5%.
The rent reset: New leases averaged $10.19/SF, an $0.88 premium to in-place rents. That gap has narrowed from $1.43 a year ago and $2.45 two years ago, signaling that landlord pricing power continues to normalize.
A tale of two markets: Sun Belt markets including Dallas, Phoenix, Atlanta and Houston continue to post solid rent growth despite heavy construction. Coastal markets are softer, particularly Seattle, where vacancy has jumped 500 bps to 13.6% following a major supply wave.
Developers are thinking bigger: Roughly 446.9M SF is under construction nationwide, equal to 2.1% of inventory. Through August, 49 projects larger than 1M SF had broken ground, with these mega-facilities accounting for more than 32% of 2026 starts by square footage.
Supply hot spots: Phoenix stands out, with construction at 6.8% of inventory and its total construction-plus-planned pipeline reaching 14.0%. Columbus follows with 4.2% of stock under construction, while Dallas sits at 3.5%.
E-commerce delivers: Online sales reached $340.2B in Q2, up 12.2% year over year, while e-commerce hit a record 20.2% of core retail sales. That continued shift toward online shopping remains a powerful long-term driver of logistics demand.

Deals keep moving: Industrial transactions totaled $60.5B through August, averaging $138/SF. Dallas led the markets in the report with $4.1B in sales, while Netflix's $400M purchase of CBS Studio Center headlined activity in Los Angeles.
➥ THE TAKEAWAY
Moving toward balance: E-commerce and large-format logistics are supporting demand, while new construction has become more disciplined. Going forward, performance will increasingly depend on location, building size, and exposure to new supply.
A MESSAGE FROM STARBOARD
Screen Every Deal Against Your Thesis

Starboard screens every deal against your buy box and your firm's own deal history, pulls comps from MSCI RCA, and builds the underwriting and memo in your templates. Every number cited to the cell.
Pass in minutes. Pursue with conviction.
*This is a paid advertisement. Please see the full disclosure at the bottom of the newsletter.
✍️ Editor’s Picks
Beyond DIY: New research reveals where CRE’s AI adoption stands—and what firms seeing real ROI are doing differently. (sponsored)
CMBS showdown: Chicago led 11 playoff metros with a 25.3% CMBS distress rate in August, while national distress eased to 10.9% as office remained the main source of trouble.
Refi recovery: Conduit CMBS refinancing is improving, with cash-out deals rising to 55.1% of classified volume through July 2026, though equity extraction remains below 2021-22 levels and acquisition lending stays subdued.
Rate reckoning: The 10-year Treasury hit 5.3%, its highest since 2002, forcing lenders to tighten underwriting as higher borrowing costs threaten refinancing, valuations and CRE deal flow.
Mortgage spike: A severe Treasury shock could push mortgage rates toward 9% if 10-year yields reach 6%-7%, adding pressure to housing affordability, CRE valuations and refinancing costs.
🏘️ MULTIFAMILY
Rent growth: U.S. rents rose 0.8% year over year to $1,665 in September, while new supply pressured Las Vegas and Cleveland as Chicago led major markets with 5.7% growth.
Rent payments: On-time rent payments at independently operated multifamily properties rose 170 bps year over year, alongside accelerating 2.2% rent growth and tighter supply, signaling firmer operating conditions.
Affordability improves: Only 30% of the 100 largest U.S. metros remained unaffordable for median earners in 2026, as new apartment supply eased rents in markets including Austin, Houston and Boise.
🏭 Industrial
Construction jumps: U.S. construction spending rose 0.9% to a $2.2T annualized rate in August, led by a 1.1% increase in private construction and residential spending.
Industrial squeeze: WareSpace invested $36.5M in 164K SF across Miami Gardens and South San Francisco, adding 210+ flexible warehouse units in supply-constrained markets.
IOS funding: Brennan Investment Group and Barings secured a $150M credit facility to build an industrial outdoor storage portfolio across Denver, Houston and Austin, with plans for further acquisitions.
🏬 RETAIL
Fuel resilience: Gas station and convenience store cap rates remain near record lows at 5.63%, as investors prioritize strong nonfuel revenue and national operators expand despite volatile fuel prices.
Publix expansion: Publix paid $83.25M for the 205K SF Airpark Plaza in Miami, expanding its real estate ownership as the grocer increasingly locks up prime South Florida locations.
Luxury trims: U.S. luxury retail leasing fell to 123K SF in H1 2026 as brands favor fewer prime locations, with 48.4% of openings under 2,500 SF and flagship demand shifting toward experience-rich spaces.
🏢 OFFICE
Midtown rebound: Manhattan office availability fell to 27.7M SF, matching March 2020 levels, while Midtown rents rose 5.4% to $85.08/SF and AI firms leased nearly 1.1M SF.
Neighborhood workclubs: Switchyards is expanding its neighborhood “third-place” clubs to 41 locations nationwide, using 2K–6K SF spaces and $129 monthly memberships for hybrid workers.
Boca listing: Macquarie listed a 379K SF Boca Raton office campus for $200M, with 86% occupancy, rents 22% below market and $6.2M in potential annual revenue gains.
Culver refinancing: Blackstone and LBA secured a $270M CMBS refinancing for the 378K SF One Culver office campus in Culver City, with Nomura providing the loan.
🏨 HOSPITALITY
Hotel slowdown: U.S. hotel performance is expected to moderate through year-end after World Cup-driven gains in June and July gave way to softer growth in August.
Convention boost: Related Ross agreed to develop a $300M, 400-room Hilton Curio near Palm Beach’s convention center through a 99-year sale-leaseback with the county.
Casino closures: Maverick Gaming plans to close eight Washington casinos, affecting 850 jobs as the Kirkland-based operator navigates Chapter 11 bankruptcy and potential ownership changes.
📈 CHART OF THE DAY

August CRE deal volume hit $102.7B, but $70B came from entity-level transactions, masking softer individual asset sales across most major property sectors.
CRE Trivia (Answer)🧠
Alexander Hamilton. Congress chartered the Philadelphia-based bank for 20 years on February 25, 1791.
More from CRE Daily
📬 Newsletters: Stay ahead of the market with local insights from CRE Daily Texas and CRE Daily New York.
🎙️Podcast: No Cap by CRE Daily delivers an unfiltered look at the biggest trends—and the money game behind them.
🗓️ CRE Events Calendar: The largest searchable calendar of commercial real estate events—filter by city or sector.
📊 Market Reports: A centralized hub for brokerage research and market intelligence, all in one place.
📈 Fear & Greed Index: A fully interactive sentiment tracker on the pulse of CRE built in partnership with John Burns Research & Consulting.

You currently have 0 referrals, only 1 away from receiving Multifamily Stress Test Model.
What did you think of today's newsletter? |
Reply