- CRE Daily
- Posts
- Buyers Press for Deeper Discounts as Higher Financing Costs Bite
Buyers Press for Deeper Discounts as Higher Financing Costs Bite
Higher rates are reopening the gap between what buyers offer and sellers will take.
Nina Dale
November 09, 2026
In partnership with

Good morning. The haggling is back in CRE, as buyers lean on sellers to reprice deals after the handshake. Requested cuts are running 5% to 10%, but sellers are giving up only 3% to 5%.
🎙️ This Week on No Cap: First Washington Realty CEO Alex Nyhan explains how his grocery-anchored portfolio abated less than 1% of rent through COVID, and why he won’t chase the highest-credit tenant for every box.

CRE Trivia 🧠
Despite brutal Minnesota winters, the Mall of America runs no central heating. What keeps it warm instead?
IN PARTNERSHIP WITH APPFOLIO
How Much Time Could You Save on Your Next Reporting Cycle?
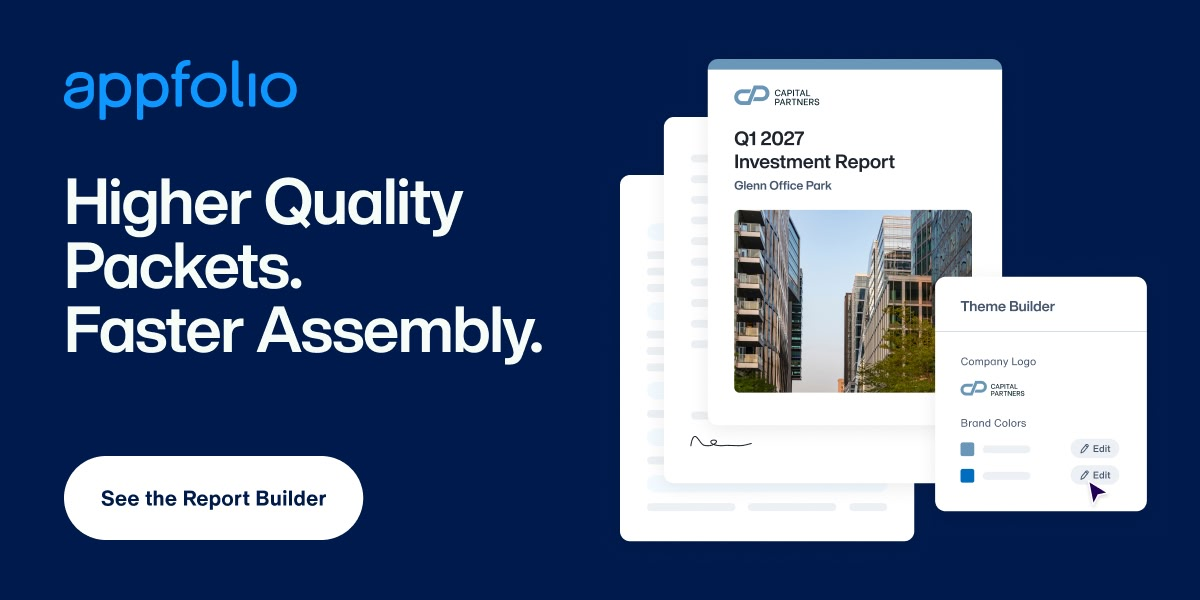
Deliver Institutional-Grade LP Reports That Look Like You Hired a Design Agency.
Investors equate report quality and timeliness with their GP’s operational maturity.
Stop juggling separate design tools, spreadsheets, and legacy portals. AppFolio Investment Manager helps GPs generate institutional-grade, custom-branded, and on-time LP reports while powering your entire end-to-end investment lifecycle in one platform.
Give your LPs an institutional-grade experience. See what your next quarterly update could look like.
*This is a paid advertisement. Please see the full disclosure at the bottom of the newsletter.
Market Snapshot
|
| ||||
|
|
The Bid-Ask Gap
The Retrade Is Back as Buyers Chase 5%-10% Discounts
Buyers are leaning harder on sellers to cut prices after signing, and sellers are meeting them only partway as higher financing costs widen the gap.
By the numbers: According to Cushman & Wakefield's October Market Matters report, buyers are requesting 5% to 10% off agreed prices, while accepted retrades have averaged just 3% to 5%. Bid-ask spreads have widened, though outcomes still vary deal by deal.
The driver: Higher borrowing costs are doing most of the damage. The 10-year Treasury climbed nearly 70 bps from its August low into early October, lifting the base rate that sets most financing even as lenders stay open for business.

The standoff: The biggest requested discounts landed on properties priced tight from the start, while deals launched at higher yields drew smaller asks. Some sellers are refusing to budge, postponing sales or pulling listings until the math improves.
The capital picture: Financing itself remains plentiful even as pricing resets. Bank loan originations are up 40% YTD and debt-fund originations 35%, so the friction is the cost of money, not its availability. CMBS spreads held firm on senior tranches, with AAA conduit spreads just 6 bps wider, though BBB- spreads blew out more than 80 bps.
A second wave: Owners who stretched their holds with back-to-back bridge loans began weighing sales over the past 45 days, which Cushman & Wakefield expects to surface in 2027. It still sees a far milder correction than the first rate-hike cycle delivered.
➥ THE TAKEAWAY
Deals clear, but on the buyer's number: Capital is available, so transactions are still getting done, just closer to what buyers offer than what sellers want. For owners facing maturities, the next 12 months may reward those who price realistically early over those who wait for rates to turn.
A MESSAGE FROM REAL PROPERTY CAPTIVE
The Insurance Strategy Wall Street Already Knows
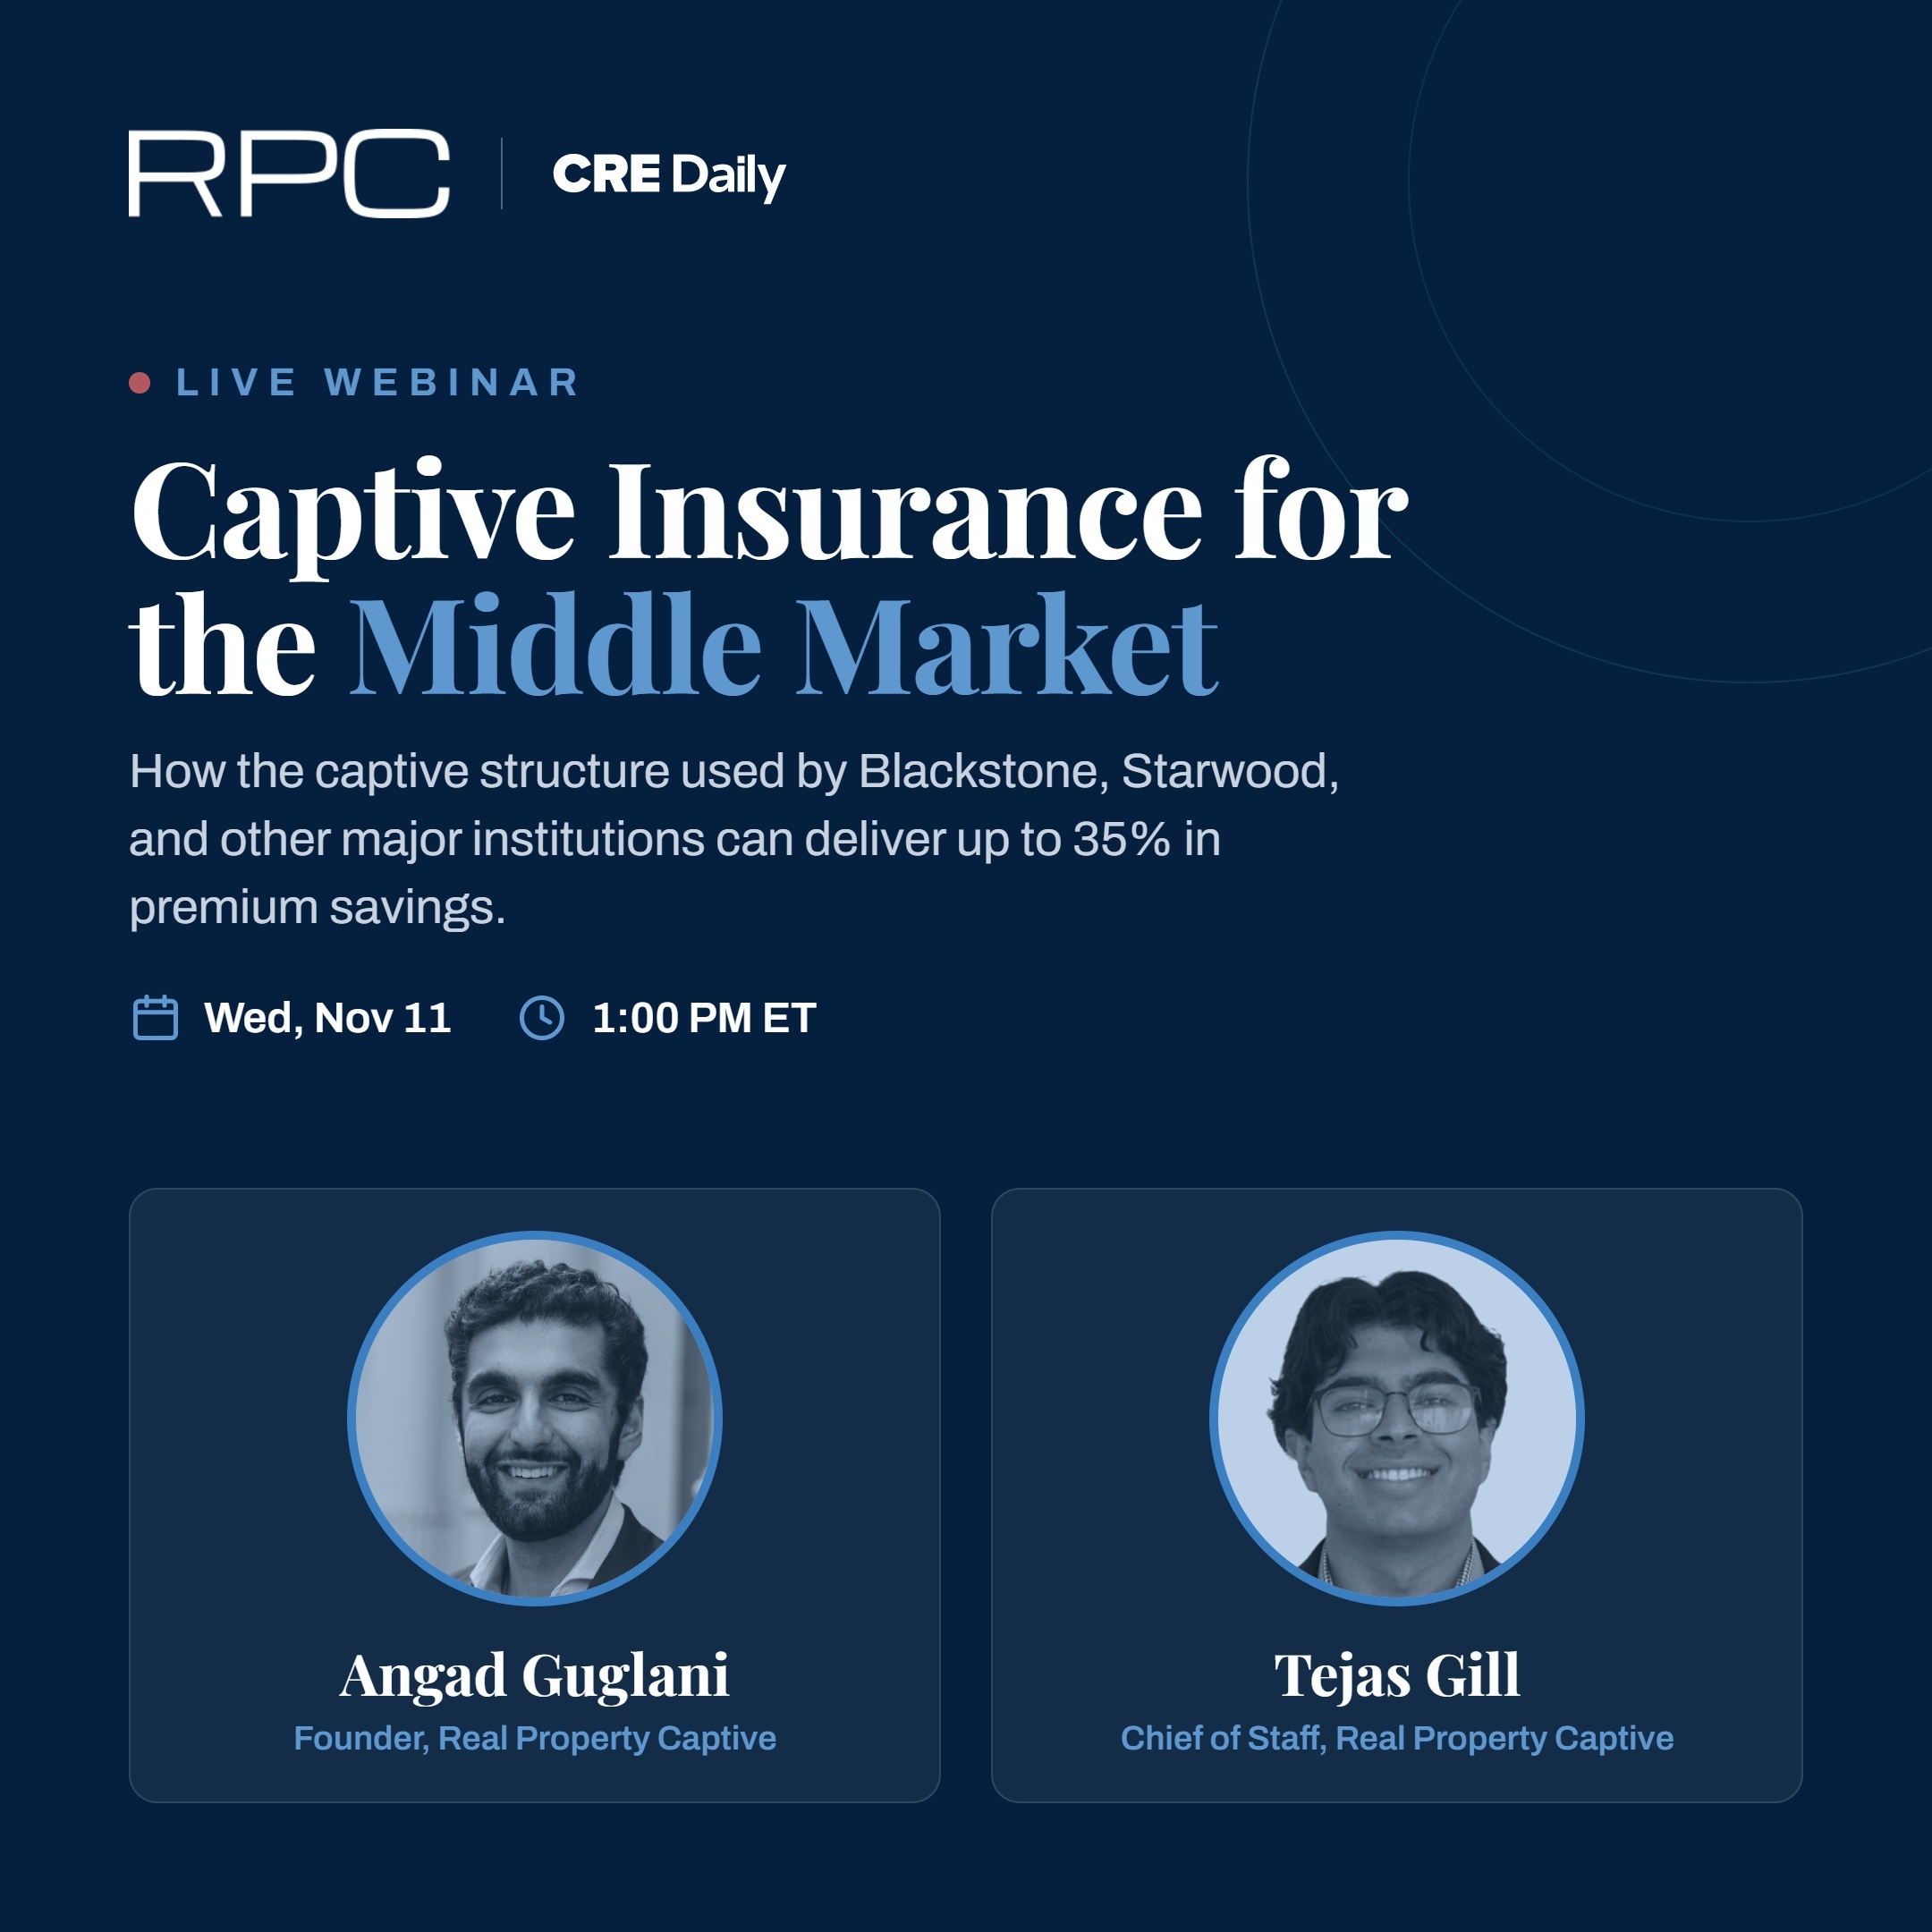
Insurance is one of the biggest expenses eating into your NOI. But what if you could take control of those costs and keep more of the underwriting profits?
Join Real Property Captivefor a free webinar exploring how real estate owners with $100M–$3B in assets can use captive insurance to reduce costs, improve NOI, and build long-term value.
Can't attend live? Register to receive the recording.
*This is a paid advertisement. Please see the full disclosure at the bottom of the newsletter.
✍️ Editor's Picks
Claude now sources CRE deals:Terrakotta's Claude Agent is disrupting the CRE industry as we speak. Brokers can now automate LLC skip-tracing, find motivated sellers, and source off-market deals. (sponsored)
Credit thaw: Bank CRE loans healed in Q2 as the noncurrent rate fell to 1.42%, the lowest since 2023, while originations jumped 29% to $9.2B.
Zone reset: Treasury fixed 6,576 new Opportunity Zones for 2027, a quarter fewer than 2018, with 39% rural and a richer tax break aimed at the countryside.
BREIT pivot: Blackstone's BREIT steered $7B of asset-sale proceeds into data centers and industrial this year, posting its best net inflows since 2022 as subscriptions ran 40% ahead.
Hiring chill: CRE hiring stayed frozen, with 2026-27 base salaries set to rise just 3.6%, the slowest pace since 2023 and down from 4.8% two years earlier.
Value rotation: Investors piled into beaten-down real estate stocks after a firm October jobs report, treating the rally as a bet on value rather than a recession hedge.
🏘️ Multifamily
Carolina crown: Raleigh and Charlotte topped Arbor's fall multifamily ranking of the 50 largest metros on fast population growth, with San Francisco third as AI hiring lifted the coasts.
Builder caution: Apartment developer confidence slipped to 41 on NAHB's Q3 production index, down five points and below the break-even 50, pointing to a thinner construction pipeline.
Supply ebbs: San Diego's apartment deliveries are slowing as its construction pipeline thins, the kind of supply pullback RealPage credits for steadying rents across once-oversupplied markets.
Turning point: Rental economist Jay Parsons argues multifamily has reached an inflection point as the supply wave crests and steady demand sets up firmer rents into 2027.
🏭 Industrial
Factory pull: A US manufacturing surge powered record Atlanta industrial demand, with Q3 net absorption doubling to 6.7M SF and leasing reaching an all-time high of 22.2M SF.
Grid risk: Texas's incoming governor has pledged a data-center moratorium that puts about 13 GW of planned projects at risk, roughly a quarter of the nation's pipeline.
Dirt deal: GFH Partners sold a US industrial outdoor storage portfolio for $113M, the latest institutional bet on the dirt lots feeding data-center and logistics construction.
Storage stall: Self-storage demand tracks housing turnover, and Green Street says sluggish home sales are capping growth even as the sector stays resilient through downturns.
🏬 Retail
Mall momentum: Simon Property raised its 2026 FFO outlook and dividend after Q3 real estate FFO rose 4.7% to $3.37 a share, with mall occupancy at 96.5%.
Loss narrows: Macerich shrank its Q3 loss to $16.7M from over $87M a year earlier as revenue and FFO rose and its premier malls pushed past 96% leased.
Holiday spend: Holiday spending will climb 9.7% to about $1,250 a shopper this year, with entertainment and experiences up 17% as buyers favor dining out over extra gifts.
🏢 Office
Cap climb: Multitenant office investment sales jumped 31.8% to $22.7B in Q3 as buyers returned at higher yields, pushing the average cap rate up nine bps to 7.58%.
Raid widens: German prosecutors raided pension giant BVK over losses on seven US real estate projects, widening a corruption probe that also swept up partner Deutsche Finance Group.
Deep red: Hudson Pacific posted a $218M Q3 loss, widened by impairments and the discounted sale of two half-empty San Francisco office towers for $65.5M.
Weeks reprieve: KBS REIT III won only weeks-long extensions on $455M of office loans against Chicago's Accenture Tower and two Arlington buildings, underscoring mounting maturity pressure.
🏨 Hospitality
Resort bet: Hyatt has built the world's largest luxury all-inclusive portfolio at 100-plus resorts, a five-year pivot that now drives roughly a fifth of its fee revenue.
Human touch: Hotels are weaving AI through most back-office tasks but holding the line at the front desk, keeping the guest welcome human even as automation spreads.
Outdoor stay: Catal Capital lent $38M to build a 341-space Margaritaville-branded RV resort in coastal Georgia, a wager on outdoor hospitality maturing into an institutional asset class.
Host buys: Host Hotels paid $374M for two hotels, the 1 Hotel Brooklyn Bridge and a Renaissance near Dallas, pushing capital into premium urban and Sun Belt rooms.
📈 CHART OF THE DAY

Private real estate returns have recovered from the steep losses of 2023, reaching positive territory in 2025 and 2026, although quarterly performance remains below the long-term average of approximately 2.1%.
CRE Trivia (Answer)🧠
Body heat, lighting, and skylights. Over a mile of skylights, thousands of light fixtures, and shoppers' body heat warm the 5.6M SF mall.
More from CRE Daily
📬 Newsletters: Stay ahead of the market with local insights from CRE Daily Texas and CRE Daily New York.
🎙️Podcast: No Cap by CRE Daily delivers an unfiltered look at the biggest trends—and the money game behind them.
🗓️ CRE Events Calendar: The largest searchable calendar of commercial real estate events—filter by city or sector.
Market Reports: A centralized hub for brokerage research and market intelligence, all in one place.
Fear & Greed Index: A fully interactive sentiment tracker on the pulse of CRE built in partnership with John Burns Research & Consulting.

Reply